
The Piton Investment Team saw concern expressed this week after the announcement of the federal deficit reaching $40T and attention to the Treasury Department’s debt repurchase plans, with talk about Treasury yields reaching a point where they signal a concern for equities. Piton’s Senior Vice-President of Research, Chuck D. Etzweiler, MBA, CIMA®, CFP®, CMT, turned to historical data about the issue, especially research by Doug Ramsey and Eric Weigel of The Leuthold Group in 2013, which proves remarkably prescient (full article at https://www.advisorperspectives.com/commentaries/2013/02/20/trying-and-failing-to-make-the-math-work-for-long-term-bonds).
In 2013, the report said, “The prevailing yield on the 10-year Treasury has provided a wonderfully accurate forecast of bond market total returns 10 years out,” with this chart in support.
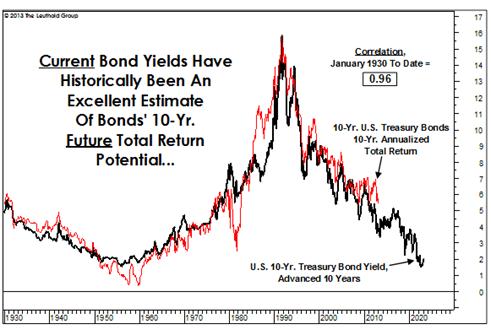
Still in 2013, the report continues, “The projected 10-year annualized total return for 10-year U.S. Treasury bonds as of January 31, 2013, is pretty straightforward: it is simply the month-end 10-year Treasury yield of 2.02%,” and the authors themselves actually expect that this would turn out to be a little high.
It’s been more than 12 years since then, but Chuck plugged in some numbers to see whether the expectations were close:

AGG = iShares Core U.S. Aggregate Bond ETF
TLT = iShares 20+ Year Treasury Bond ETF
Another pattern from the article was also fascinating and helpful. There was a Bear Market in Bonds with a following remarkably symmetrical Bull Market following, with the apex at the September 1981 peak. Here is the chart from 2013:

Chuck put this pattern in the context of ups and downs across a broader historical swath:

Very much as anticipated in 2013, rates have taken a rising turn. Not bad.
But what about the current concern? Does this mean a danger signal for equities? Well, currently the U.S. 10-year Treasury yield is a little above 4.7% and trending upward. The following table, again from the 2013 report, covers 1962-2013, correlating the 10-year yield to the S&P 500.

In this table, the flip to negative is at about 5.67, and we are not there yet, but the trend is one to continue watching. Historical data and the perspective it brings help the Piton Investment Team stay oriented when they make decisions about Piton Portfolios. From the research here, long-term trends in the bond market seem to spread out over wider lengths of time than is typically the case for equities. The team also noted the relative volatility and reliability of growth of bonds compared to equities. Stocks can be extremely volatile in the short term but over the long term have historically turned out to yield overall strong returns. Conversely, bonds are a more straightforward pick in the shorter term but over the longer run can have disappointing yields compared to equities (as in the lengthy bear market charted above). Prudent portfolio construction, matched to a client’s specific situation (including a timeline for their goals) should be diversified in multiple ways, including both stocks and fixed income, as appropriate. Data and trends like these help guide the team in recommending what suits Piton clients best. evaluate and update their portfolios, always with the goal of maintaining portfolios that serve the client’s goals the best.